Comfortable living in Miami takes more than covering rent. That gap is central to understanding the cost of living versus rental income in Miami.
Rent is only one part of the equation. Location, household expenses, and the difference between rent collected and income left after property costs all shape the picture for renters and investors. How does Miami compare with other Florida and U.S. markets, and what income can support a comfortable lifestyle? This article covers typical living costs, salary needs, neighborhood rent differences, and how rental returns relate to property values. It offers a practical framework for weighing a move to Miami against an investment, without treating rental income as a substitute for a salary.
Key Takeaways
- Use the estimated annual income range for a single renter as a starting point, then account for your household’s needs and preferred lifestyle.
- Compare neighborhoods before setting a housing budget, since Miami-area rents can vary substantially by location.
- Separate rental income from potential investment return by weighing property costs alongside the rent a home could bring in.
- Consider how Miami’s living costs compare with other markets to better assess whether a move or property investment fits your goals.
How Much Do You Need to Earn to Live Comfortably in Miami?
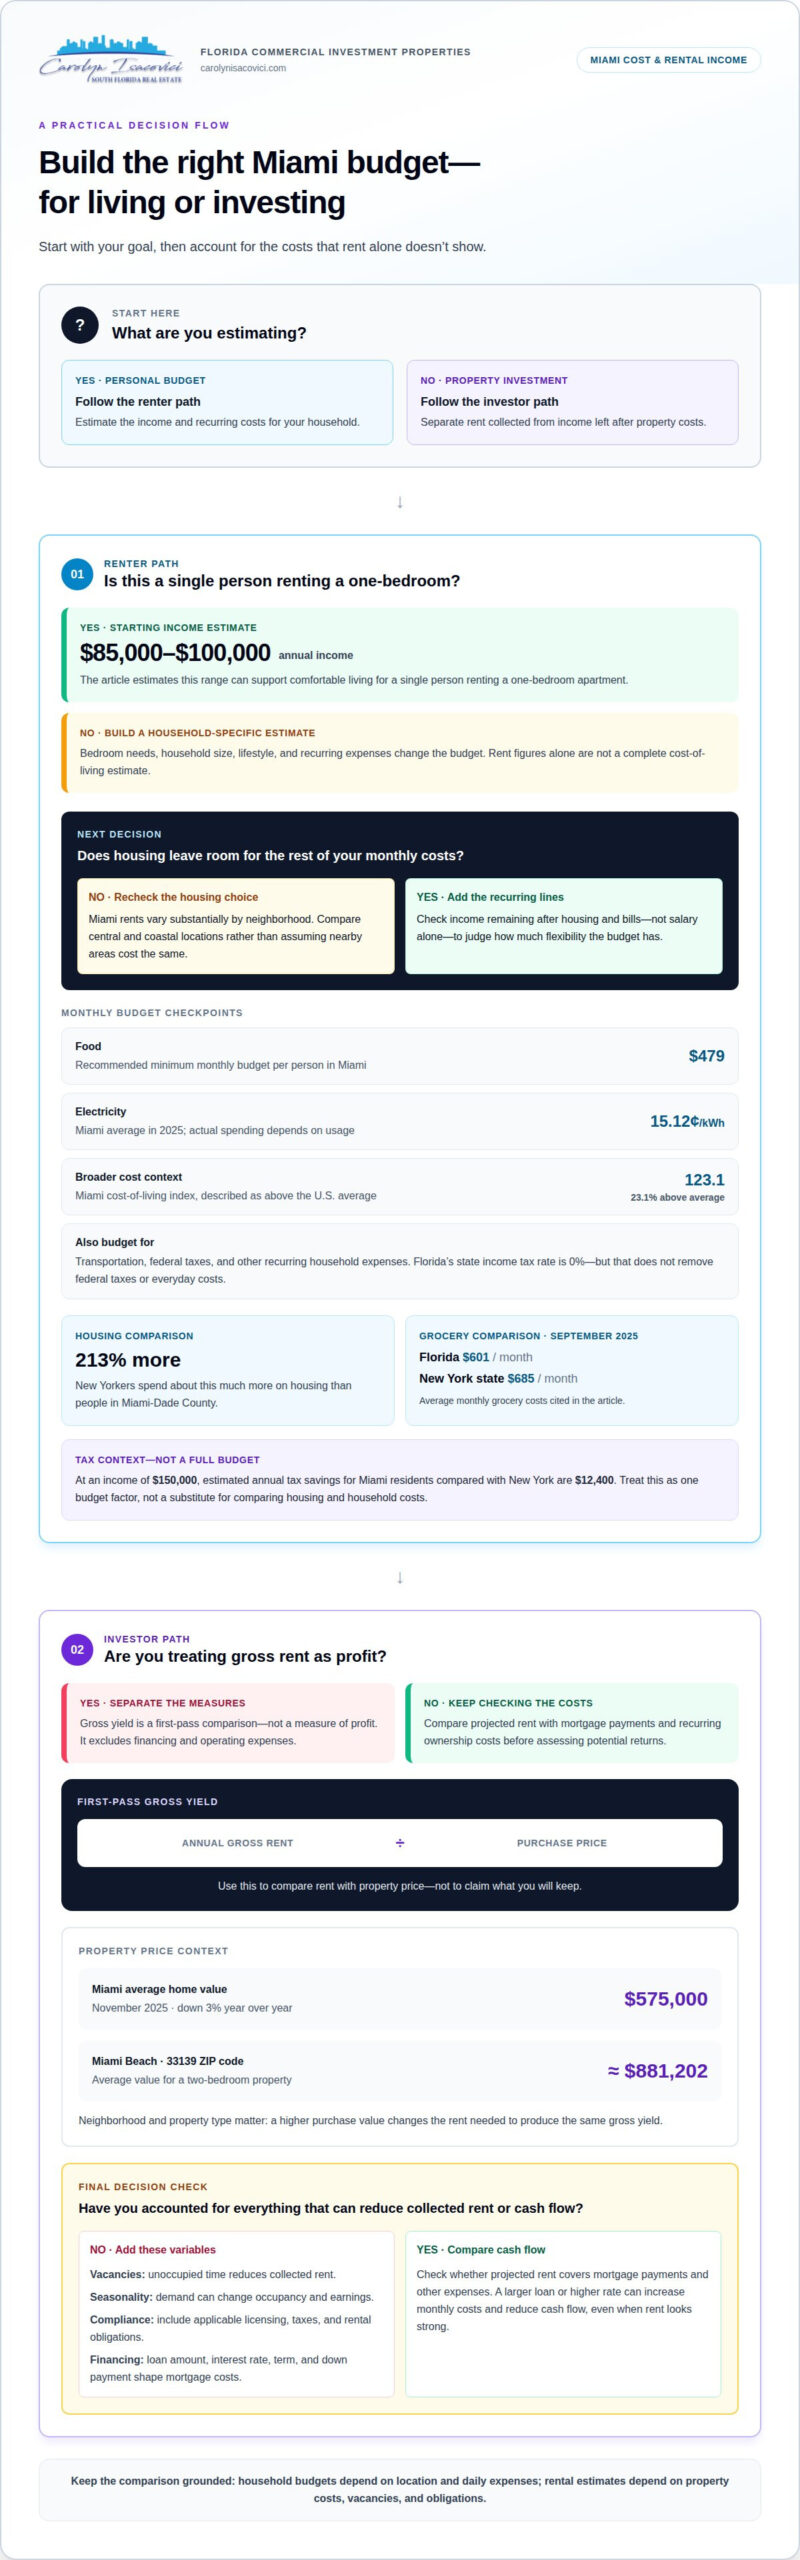
For a single person renting a one-bedroom apartment, an estimated annual income of $85,000-$100,000 can support comfortable living in Miami.
Florida’s state income tax rate is 0%. That can support take-home income compared with states that levy individual income tax, but it doesn’t remove federal taxes or everyday expenses. At an income of $150,000, estimated annual tax savings for Miami residents compared with New York are $12,400. Treat that comparison as one part of your budget, not as a substitute for comparing housing and household costs.
Comfort depends on how rent fits alongside other priorities. Choosing a less expensive home can leave more room for savings, transportation, and leisure. A higher-cost apartment may reduce that flexibility on the same salary. For a useful cost-of-living comparison, look at the income remaining after housing and recurring bills, not salary alone.
What are Miami’s short-term rental rules, licensing requirements, and taxes? Requirements and tax treatment depend on the property’s location, permitted use, and rental arrangement. Include applicable compliance costs and obligations in your budget rather than treating expected rent as net income.
What vacancy rates and seasonal trends affect Miami rental income? Vacant periods reduce collected rent, and seasonal demand can change occupancy and earnings. A realistic projection accounts for unoccupied time across the year instead of assuming every available night generates income.
A practical income estimate starts with three decisions:
- Choose a housing budget that leaves room for essential monthly expenses.
- Account for federal taxes and recurring costs alongside Florida’s 0% state income tax.
- For a rental property, distinguish gross rent from income remaining after vacancies and operating obligations.
Miami cost-of-living comparisons
Miami housing costs vary sharply by neighborhood, so a citywide figure can conceal meaningful differences. Location is therefore a major factor in both household budgeting and rental-property estimates.
Central and coastal areas can have very different price points. Compare them by expected rent and the lifestyle or access each offers, rather than assuming nearby neighborhoods have similar costs.
Housing comparisons with New York are striking: New Yorkers spend about 213% more on housing than people in Miami-Dade County. Other household costs also differ. In September 2025, average monthly grocery costs were $601 in Florida and $685 in New York state.
Use these comparisons to plan, not as a guarantee of personal savings. Lower rent may leave more room for other expenses, while a coastal address can take up a larger share of the budget. Grocery habits, dining, household size, and commuting needs also matter. When planning a move, weigh housing costs against the daily routines a neighborhood supports.
For readers weighing a home purchase in the area, Miami residential real estate options can help frame the decision around location and housing needs.
What is the average cost of living in Miami for one person and a family?
Miami’s cost-of-living index is 123.1, described as 23.1% above the U.S. average. Housing is a major part of the monthly budget, and the number of bedrooms a household needs changes the picture. A one-person budget and a family budget therefore shouldn’t rely on the same rent estimate.
A studio may suit a single renter, while a family may need more bedrooms. These figures describe rent, not total living costs, so they are not a complete monthly budget.
Food adds another household-level variable. The recommended minimum monthly food budget is $479 per person in Miami. Use that per-person benchmark to think through household needs, then adjust for grocery habits and the number of people sharing meals. A family’s food budget won’t match a single adult’s simply because both live in the same city.
Transportation and utilities also belong in the calculation. In 2025, electricity averaged 15.12¢ per kilowatt-hour in Miami. Actual electricity spending depends on usage, so household size and the home’s cooling needs can affect the bill even when rent is similar.
For a clearer estimate, build separate monthly lines for rent, food, transportation, and electricity. This approach makes family needs visible without assuming everyone spends equally. It also helps a single person see which costs stay fixed and which rise with household size. The 123.1 index provides broader context, while these local expenses show where a personal budget may diverge.
How do Miami rental yields compare with property prices and mortgage costs?
Rental yield relates a property’s price to the rent it earns. Divide annual gross rent by the purchase price for a first-pass comparison, not a measure of profit, since this excludes financing and operating expenses. For the cost of living versus rental income in Miami, the distinction separates rent collected from money remaining after expenses.
Miami’s average home value was $575,000 in November 2025, down 3% year over year. In Miami Beach’s 33139 ZIP code, the average value for a two-bedroom property was around $881,202. The higher purchase value changes the rent needed to produce the same gross yield. Neighborhood and property type therefore matter as much as citywide averages.
Mortgage costs affect how much cash remains after rent arrives. The loan amount, interest rate, term, and down payment shape required payments. A larger loan or higher rate can increase monthly costs and reduce cash flow, even when rent looks strong. For the cost of living versus rental income in Miami, compare projected rent with mortgage payments and recurring ownership costs before assessing potential returns.
Consider a two-bedroom property in Miami Beach. Estimate rent based on the property type and neighborhood, not a broad Miami average. Gross yield can compare that estimate with the purchase price, while cash flow indicates whether rent covers mortgage payments and other expenses. Neither measure alone accounts for vacancy or future maintenance.
For a sound comparison, assess these factors together:
- Purchase price: use the property’s relevant location and type.
- Rent estimate: align it with comparable homes in the same area.
- Financing: account for the loan structure and monthly payment.
- Ownership costs: include ongoing expenses and periods without rent.
Looking at Miami investment properties? Explore investment property opportunities with price, rent, and financing considered together.
Florida Commercial Investment Properties
Florida Commercial Investment Properties helps connect Miami housing costs and rental potential with real estate decisions. If you’re weighing a move, its residential property sales can help you consider a home purchase in light of your household’s needs. If you’re assessing rental returns, the firm’s investment property sales offer a way to explore acquisitions with income potential in mind.
The right comparison depends on your goal: a place to live, an investment, or a broader real estate holding. Commercial property sales and new construction homes may also suit particular plans. Weigh location, expected rent, purchase value, and ongoing costs rather than relying on rent alone.
For help matching your Miami housing or investment goals with real estate options, contact Florida Commercial Investment Properties.
Turn your Miami comparison into a clear next step
The cost of living versus rental income in Miami is most useful as a decision framework, not a single pass-or-fail figure. Decide whether your priority is choosing a home, developing an investment plan, or balancing both. Then weigh the trade-offs that matter to you, including location, space, expected rental performance, and costs over time.
A focused real estate conversation can connect those priorities to your next move. Bring your goals and the factors shaping your decision to explore which direction makes sense. Whether you’re considering a home or an investment property, a thoughtful comparison can clarify the path forward.
Contact Florida Commercial Investment Properties to discuss your real estate goals and next steps. With a clear view of what matters most, you can approach Miami’s opportunities with greater confidence.
Frequently Asked Questions
Is Miami an Expensive City to Live In?
Yes, Miami can be expensive, particularly for households seeking central or coastal housing. Rent is only one part of a budget: transportation, food, utilities, and household size also affect monthly spending. A renter living alone faces different trade-offs from a family needing more bedrooms. Compare costs against your own routines and preferred location before deciding what income will feel comfortable.
What Are the Ongoing Costs Associated with Owning a House or Condo in Miami?
Owners should budget for more than mortgage payments. Recurring expenses can include property taxes, homeowners insurance, utilities, maintenance, and repairs. Condo owners may also pay association fees and assessments, depending on the building and its governing arrangements. An aging air-conditioning system, for example, can create a repair cost renters do not pay directly. Include these expenses when comparing a home’s carrying costs with potential rent.
What Expenses Should I Consider When Moving to Miami?
Plan for the move, housing payments, utilities, food, and transportation. A household relocating from outside Florida may also need to budget for travel, temporary accommodation, and moving belongings. After arrival, commute patterns and household size shape recurring costs. Someone working far from home, for example, may prioritize transportation differently from a remote worker. Account for both upfront moving needs and regular monthly expenses.
What Is the Average Rent in Miami?
There isn’t one useful rent figure for every Miami home. Two-bedroom apartment rentals on the market typically range between $2,300 and $4,900 per month. The spread reflects differences in location and property characteristics, so a single average can be a poor match for a specific search. Compare rentals with similar bedroom counts and locations to understand which asking rents are relevant to your housing plans.
What are typical monthly rents in Miami by neighborhood and apartment size?
Apartment size and neighborhood both affect rent. That figure is a neighborhood-specific reference, not a citywide rate or a guide to every building. In other areas, compare homes with the same bedroom count and similar features. Distance from work, transit, and everyday destinations can also clarify which rent trade-offs matter to you.
What is the average rental income for Miami landlords by property type?
Rental income varies with location, size, condition, and rental arrangement, so one average cannot represent every Miami landlord. A studio and a multi-bedroom home serve different needs, while condos and houses can have different ongoing costs. Estimate gross rent using comparable properties, then account for vacancies, maintenance, and ownership expenses to understand what income may remain.